Tracing the origins
Where the quiet fracture in market liquidity first revealed itself
In the winter of 2019, a small team of former central bank researchers gathered in a borrowed conference room in Sydney. They had spent years watching institutions build elegant models that assumed funding would arrive precisely when needed. Then they watched those same models fail, repeatedly, during moments of market stress. The problem was not ignorance. It was a blind spot. The mathematics of stochastic liquidity mismatch had been treated as a footnote rather than a foundation. That afternoon, the decision was made to build something different: a platform devoted entirely to the dynamics that static models cannot capture.
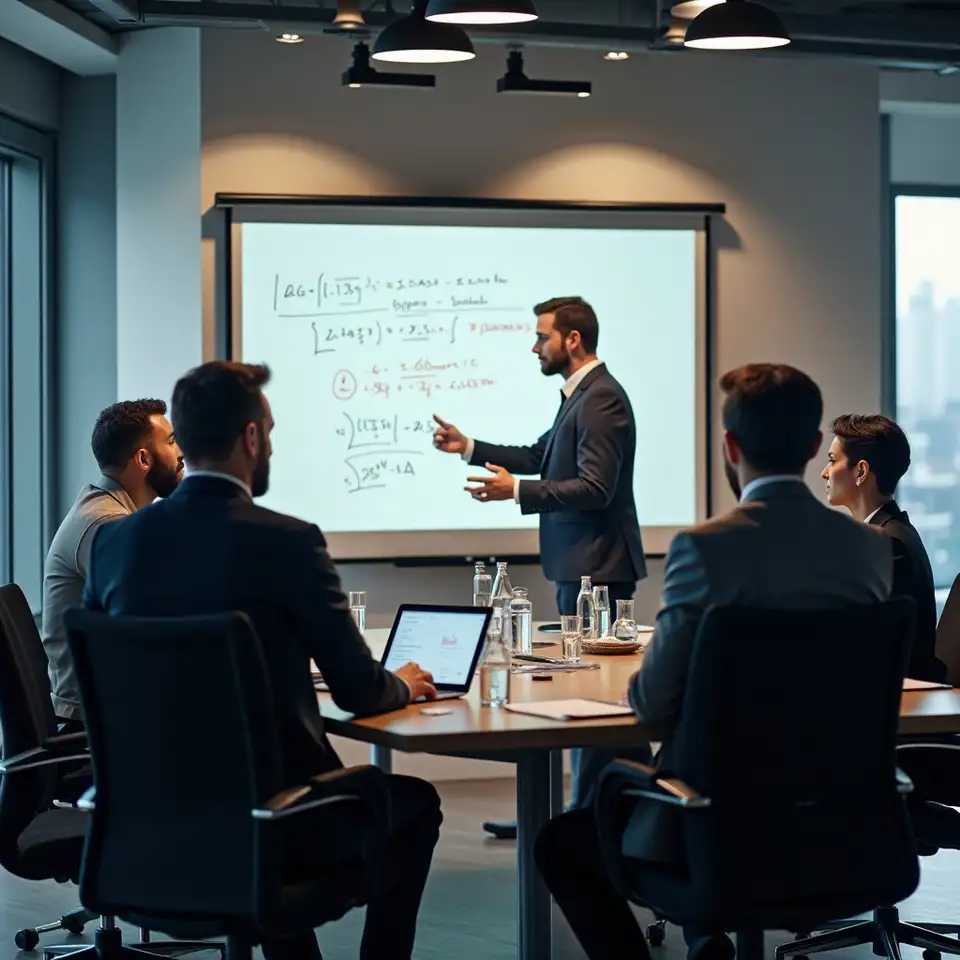
The conviction that liquidity risk moves in ways models refuse to predict
Every institution carries a hidden vulnerability: the gap between when capital is needed and
when it actually arrives. That gap does not behave like a fixed interval. It breathes,
contracts, and collapses under stress in ways that deterministic frameworks miss entirely.
01
Static assumptions are the first casualty of crisis
When markets seize, the assumption that liquidity arrives on schedule becomes
fiction. The platform treats every funding horizon as a distribution, not a date.
Institutions learn to ask not when capital will be available, but what probability
they can tolerate for it not being there.
02
Mismatch dynamics deserve their own language
Asset liquidity and funding needs evolve on separate clocks, driven by different
shocks. Conflating them into a single risk metric obscures the very fragility it
claims to measure. The curriculum builds fluency in the stochastic processes that
govern each side independently.
03
Empirical honesty over theoretical elegance
A model that cannot survive contact with historical stress episodes is not merely
wrong, it is dangerous. Every methodology taught on the platform is validated
against documented episodes of market dysfunction, from the global financial crisis
to recent sovereign funding squeezes.
04
Institutional memory decays faster than models update
The personnel who lived through previous liquidity crises retire, rotate, or simply
forget. The platform exists partly as an institutional memory bank, preserving the
analytical lessons of past stress events and transmitting them to new generations of
risk professionals.
The researchers and practitioners who built the analytical framework
The core team combines backgrounds in central bank supervision, investment bank treasury functions, and academic quantitative finance. Each member was selected not for theoretical distinction alone, but for having witnessed liquidity mismatch dynamics from the inside during periods of genuine market stress.
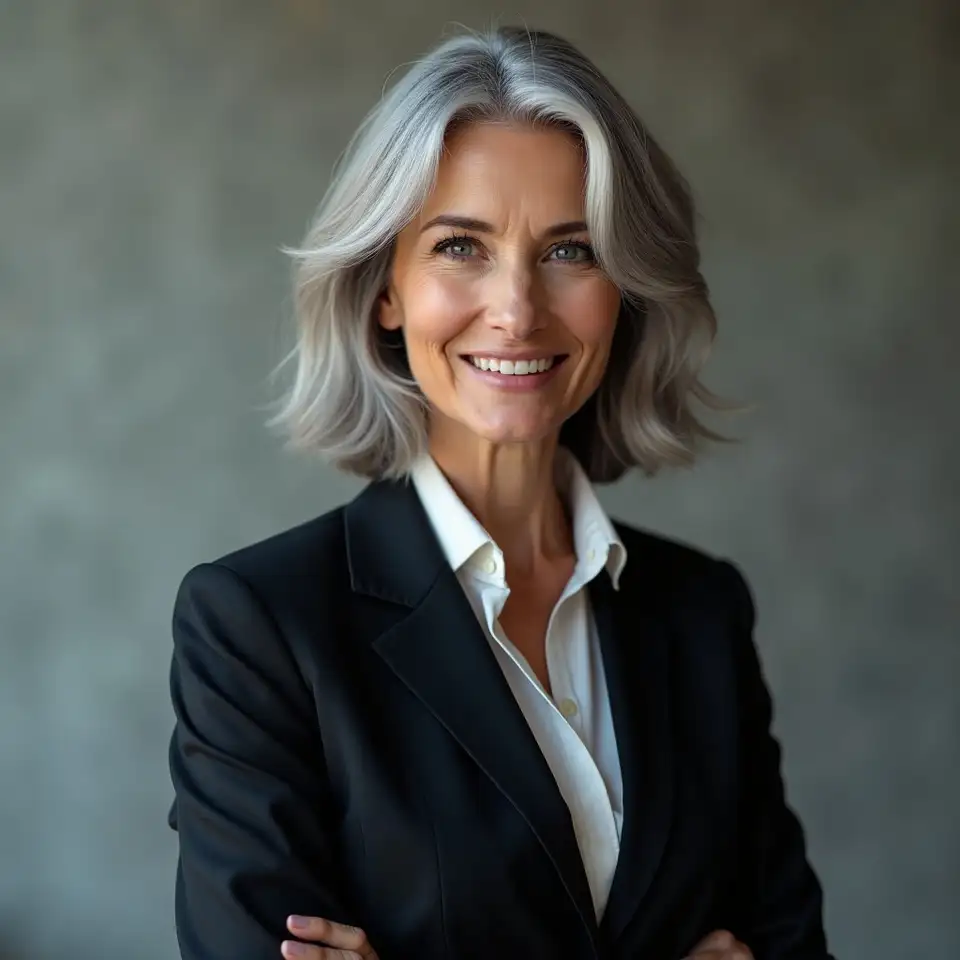
Dr. Eleanor Whitmore
Founding Director, Stochastic Modelling
Sydney, Australia
Former senior economist at a major Asia-Pacific central bank, where she led the analytical response to two separate episodes of short-term funding market stress. Her post-crisis reports remain referenced in supervisory guidance documents.
Core analytical specialisations
Continuous-time stochastic processes
Funding liquidity modelling
Regulatory framework design
Crisis episode reconstruction
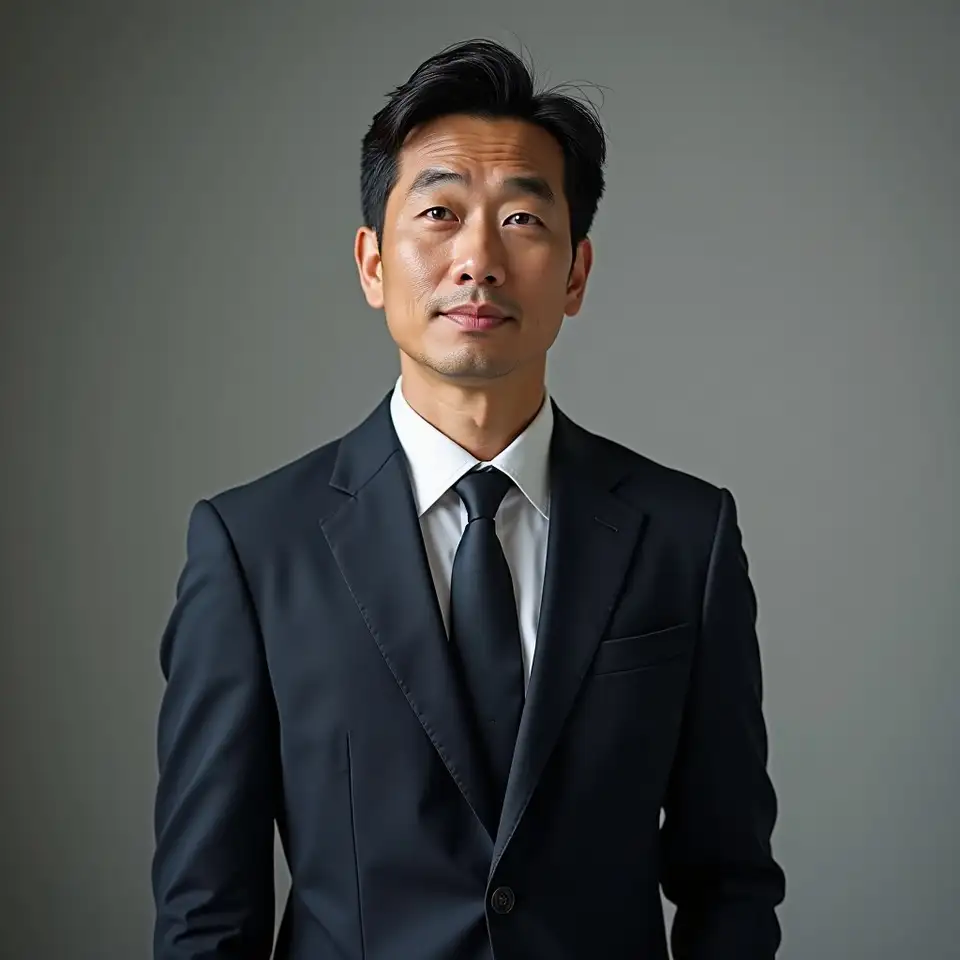
Marcus Chen-Williams
Head of Treasury Analytics
Singapore
Spent fourteen years in treasury functions at two global banks, including direct responsibility for USD funding operations during the 2019 repo market disruption. Joined the platform to bridge the gap between analytical theory and trading floor reality.
Practical implementation focus
Collateral optimisation analytics
Intraday liquidity monitoring
Stress testing architecture
Cross-border funding structures
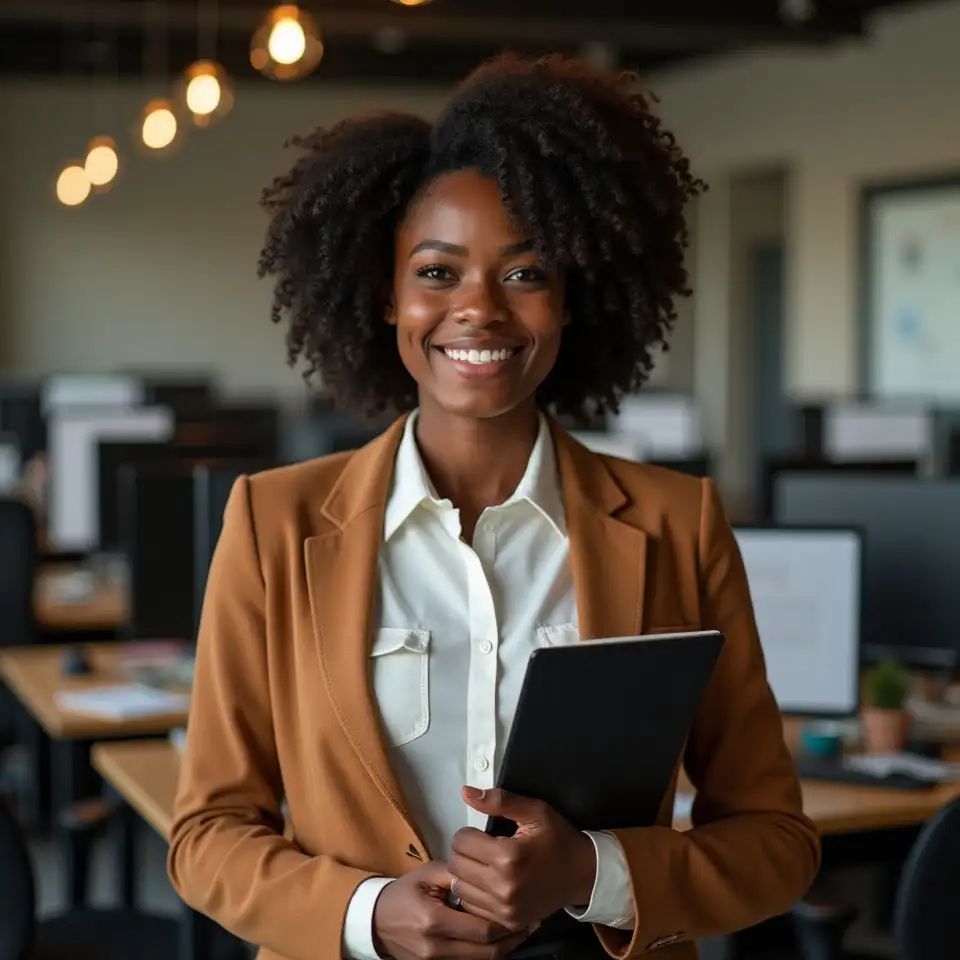
Professor Amara Osei-Bonsu
Lead Researcher, Asset Liquidity
London, United Kingdom
Holds a chair in quantitative finance at a leading European business school and has served as an expert witness in three major regulatory proceedings concerning liquidity risk measurement failures. Her empirical work on asset liquidation timelines is widely cited.
Academic and market interface
Market microstructure analysis
Fire sale dynamics modelling
Bid-ask spread decomposition
Empirical market impact research
James R. Holloway
Director, Institutional Programs
New York, United States
Former head of liquidity risk at a systemically important financial institution, where he redesigned internal reporting to expose stochastic mismatch exposures previously invisible to senior management. Leads program adaptation for North American institutional clients.
Program design and delivery
Executive analytical workshops
Institutional capability assessment
Cross-functional risk communication
Board-level risk reporting
Key moments in the development of the analytical framework and its dissemination to
institutional practitioners.
2019
Initial research consolidation
The founding team completed a comprehensive review of liquidity mismatch episodes from 2007 to 2019, identifying a systematic pattern: institutions consistently underestimated the variance in funding arrival times relative to asset liquidation horizons. This empirical finding became the analytical cornerstone of the platform's methodology.
2021
First institutional engagement
A major Asia-Pacific banking group commissioned a bespoke analytical review of its stochastic liquidity exposure. The engagement revealed previously unmeasured concentrations in wholesale funding that deterministic models had classified as benign. The methodology proved its practical value in a live institutional context.
2023
Curriculum formalisation and expansion
Building on accumulated institutional experience, the platform structured its analytical frameworks into modular programs adaptable to different balance sheet types. The curriculum expanded beyond banking to encompass insurance groups, asset managers, and sovereign wealth vehicles with distinctive liquidity profiles.
2025
Multi-asset class framework release
The platform published its integrated framework for stochastic liquidity mismatch across fixed income, derivatives, and less liquid asset classes. The release included calibrated models for correlation breakdown during stress episodes, addressing a longstanding gap in cross-asset liquidity risk measurement.
What governs the work
The principles that shape every analytical framework, every institutional engagement, and every research publication released through the platform.
Intellectual honesty
No methodology is presented as complete or beyond challenge. Every framework carries explicit assumptions, known limitations, and conditions under which it may fail. Institutions deserve to understand not only what a model predicts, but where it breaks.
Empirical validation
Analytical tools must survive contact with historical reality. Every model taught or deployed through the platform is tested against documented episodes of market dysfunction. Theory that cannot explain the past has no authority to predict the future.
Practical relevance
Sophistication serves no purpose if it cannot be operationalised within existing institutional constraints. The platform prioritises analytical frameworks that treasury functions can actually implement, not elegant constructions that remain theoretical exercises.
Ethical application
Quantitative methods carry moral weight. The platform refuses engagements intended to obscure risk rather than illuminate it, and maintains the right to decline institutional relationships that would compromise analytical independence or public trust.
Continuous refinement
Market structure evolves, and so must analytical approaches. The platform commits to ongoing revision of its frameworks as new data emerges, new instruments proliferate, and new episodes of dysfunction provide fresh empirical material.
Engage with the platform
Upcoming briefings
The platform hosts periodic analytical briefings examining recent episodes of market dysfunction through the lens of stochastic liquidity mismatch. These sessions are open to institutional risk professionals and provide early access to emerging research findings. Registration is limited to maintain analytical depth and participant interaction.
Institutional partnerships
For organisations seeking to embed stochastic liquidity analytics into their risk management infrastructure, the platform offers structured engagement pathways. These range from targeted analytical reviews to comprehensive capability building across treasury, risk, and executive functions.
Research collaboration
The platform maintains active research partnerships with academic institutions and supervisory bodies. Collaborative projects focus on empirical validation of liquidity mismatch models and the development of stress testing methodologies for evolving market structures.
Direct inquiry
Specific questions about analytical frameworks, program structures, or institutional engagement terms can be addressed directly. The platform's team responds to substantive inquiries within two business days, with detailed responses to complex analytical questions.